Jump to Content
Aerospace Maintenance Chemicals Market Size & Industry Share - Growth Trends & Forecasts (2026 - 2034)
Aerospace Maintenance Chemicals Market Size & Insights
The aerospace maintenance chemicals market size was valued at USD 9.26 billion in 2025 and is projected to grow from USD 9.58 billion in 2026 to USD 14.62 billion by 2034, at a CAGR of 5.40% from 2026 to 2034, according to a recent report from Consegic Business Intelligence.
The aerospace maintenance chemicals market growth is driven by several factors such as the rising air travel trend, an aging global aircraft fleet requiring intensive maintenance, repair, and overhaul (MRO), strict safety and environmental mandates, and growing demand for eco-friendly, low-emission cleaning and corrosion-control formulations.
Aerospace Maintenance Chemicals Market Statistics:
- Current Market Size: USD 9.26 Billion
- Forecast Market Size: USD 14.62 Billion
- CAGR: 5.4%
- Largest Segment: The solvent-based segment accounted for the largest revenue share in the market in 2025.
- Fastest-Growing Segment: The water-based segment is anticipated to register the fastest CAGR during the forecast period.
- Largest Geographic Market: North America
- Fastest-Growing Geography: Asia Pacific
- Major Companies: Henkel AG & Co. KGaA (Germany), 3M (United States), PPG Industries Inc. (United States), BASF SE (Germany), Exxon Mobil Corporation (United States), Eastman Chemical Company (United States), Dow (United States), Socomore (France), Callington Haven Pty Ltd. (Australia), Arrow Solutions (United Kingdom), and others.
- Key Technological/Commercial Development: Rising Global Air Passenger Traffic and Fleet Expansion, Adoption of Advanced Composite Materials & Modern Airframes, Integration of Artificial Intelligence (AI) in MRO & Inventory Planning, and Supply Chain Shifts & Multi-Sourcing Strategies.

Recent Events and Their Impact on the Aerospace Maintenance Chemicals Market
The aerospace maintenance chemicals industry is being influenced by evolving consumer preferences, regulatory developments, research, and increasing advancements. The following developments highlight key factors shaping market growth and competitive dynamics.
|
Recent Development |
Impact on the Aerospace Maintenance Chemicals Market |
|
Stricter Environmental & Compliance Regulations |
Compels manufacturers and MRO providers to shift away from hazardous chemical formulations (such as toxic paint strippers and harsh solvents), accelerating the demand for eco-friendly, bio-based, and low-VOC alternatives. |
|
Rising Global Air Passenger Traffic and Fleet Expansion |
Increases flight frequency and utilization rates, driving routine maintenance requirements and generating sustained, high-volume demand for exterior/interior cleaners, degreasers, and hydraulic fluids. |
|
Adoption of Advanced Composite Materials & Modern Airframes |
Requires specialized, highly compatible chemical formulations and precise process controls to prevent material degradation, changing procurement criteria toward lifecycle performance. |
|
Integration of Artificial Intelligence (AI) in MRO & Inventory Planning |
Streamlines chemical selection, improves inventory traceability, reduces shelf-life expiration waste, and optimizes maintenance execution schedules. |
|
Supply Chain Shifts & Multi-Sourcing Strategies |
Mitigates inventory vulnerability arising from chemical supply disruptions, encouraging localized distribution networks and resilient procurement frameworks among major MRO hubs. |
|
Focus on Worker Safety and Reduction of Hazardous Exposure |
Drives innovation in less toxic chemical compositions, reducing occupational health hazards for technicians and lowering long-term compliance and liability costs for operators. |
What is Aerospace Maintenance Chemicals?
Aerospace maintenance chemicals are specialized formulations used to clean, degrease, de-ice, strip paint from, and protect airframe structures, engines, and interior components to prevent corrosion and ensure safe, efficient flight operations. Moreover, aerospace maintenance chemicals help in preventing aircraft structural deterioration, ensuring regulatory compliance with strict safety standards, and safely removing contaminants without damaging sensitive metals or composite structures.
For market analysis, aerospace maintenance chemicals primarily includes cleaners and degreasers, de-icing fluids, paints, coatings & paint strippers, adhesives & sealants, lubricants & hydraulic fluids, corrosion inhibitors, and others. It can be used for aircraft interior and exterior maintenance applications.
Key Growth Drivers in the Aerospace Maintenance Chemicals Market
Expansion of Global Commercial Fleets and Air Passenger Traffic
- Rising Flight Frequencies: Growth in global air passenger traffic and expanding route networks result in higher aircraft utilization, directly accelerating routine maintenance cycles.
- Commercial Fleet Growth: The continuous delivery and expansion of commercial aircraft fleets create sustained, high-volume consumption of essential maintenance chemicals, thereby driving the aerospace maintenance chemicals industry growth.
- Aging Aircraft Maintenance:A significant portion of active global fleets requires intensive, frequent maintenance, corrosion control, and deep-clean procedures to extend operational lifecycles.
- Rise in Business and Regional Aviation: Increased demand for private jets, regional turboprops, and business aviation expands niche procurement channels for specialized detailing and servicing chemicals.
Advancements in Aircraft Materials and Advanced Composites
- Lightweight Composite Integration: Modern airframes increasingly incorporate advanced carbon-fiber composites and lightweight alloys that demand chemically compatible cleaning and stripping agents, further driving the aerospace maintenance chemicals market trends.
- Specialized Coatings Protection: High-performance primers, mil-spec coatings, and exterior treatments require precise chemical balancing to prevent structural degradation and surface damage.
- Lifecycle Performance Focus: Procurement criteria are shifting away from generic unit costs toward advanced formulations that ensure long-term asset protection and material integrity.
- Precision Chemical Compatibility: Tighter manufacturing tolerances demand rigorously tested solvents and sealants to prevent galvanic corrosion or chemical incompatibilities on sensitive surfaces.
Stricter Environmental Mandates and Regulatory Compliance
- Eco-Friendly and Low-VOC Transitions: Regulatory frameworks, such as REACH and EPA standards, compel manufacturers and MRO facilities to phase out hazardous chemicals and toxic paint strippers.
- Demand for Bio-Based Alternatives: Increasing compliance pressures drive significant R&D investments into green solvents, aqueous cleaners, and biodegradable washing agents.
- Disposal and Lifecycle Governance: Strict regulations governing chemical waste managementincentivize facilities to adopt sustainable products that minimize environmental footprint and hazardous disposal costs.
- Worker Safety Initiatives: Regulations targeting occupational health exposure push operators toward low-toxicity formulations that safeguard technician well-being.
Optimization of Logistics and Distribution Channels
- Strategic Third-Party Alliances:Aerospace maintenance chemical producers are forming closer distribution partnerships with global chemical aggregators, vastly improving product shelf-life availability for remote MRO hubs.
- E-Commerce Procurement Systems:The shift toward digital B2B marketplaces enables faster, streamlined cross-border supply chains for niche chemicals, preventing costly technical groundings.
- Pre-Mixed and Ready-to-Use (RTU) Packaging:Supplier transitions toward pre-saturated wipes and precisely portioned chemical packaging reduce handling waste and lower overall shipping weight overheads.
- Localized Material Warehousing:Chemical manufacturers are building dedicated regional storage facilities close to major international airport hubs to significantly decrease local transit lead times.
Aerospace Maintenance Chemicals Market Opportunities
Development and Commercialization of Bio-Based and Eco-Friendly Formulations
- Green Solvents and Aqueous Cleaners: High demand for replacing toxic or hazardous chemicals creates a major market opportunity for biodegradable, low-VOC, and water-based cleaning alternatives.
- Next-Generation Paint Strippers: Opportunities exist to develop non-toxic, eco-compliant paint removal agents that comply with stringent environmental standards, such as REACH and EPA rules, without compromising stripping efficiency.
- Sustainable Packaging and Supply: Chemical manufacturers can gain competitive advantages by offering bulk, recyclable, or reduced-waste packaging configurations tailored to modern MRO green initiatives.
- Regulatory Pre-Compliance: Formulators who design products ahead of upcoming environmental bans can capture high-margin early adoption contracts from leading commercial airlines.
Advanced Chemical Compatibility for Composite Airframes and Lightweight Materials
- Specialized Surface Treatments: The increasing integration of carbon-fiber-reinforced polymers (CFRP) and advanced lightweight alloys creates demand for specialized coatings, sealants, and compatibility-tested cleaning agents.
- Corrosion Inhibitors for Multi-Material Structures: Opportunities for formulating advanced vapor and contact corrosion inhibitors that prevent galvanic corrosion at joints where dissimilar materials meet.
- Lifecycle Performance Products: Shifting procurement criteria from unit-cost models to asset lifecycle preservation allows premium chemical vendors to market high-performance protective products.
- Precision Application Solutions: Developing specialized chemical systems that work effectively with modern automated application tools or dry-ice cleaning tech.
Expansion in Emerging Aviation Hubs and MRO Infrastructure
- High-Growth Regional Markets: Rapid fleet expansions and airline network scaling across the Asia-Pacific region and Middle East offer lucrative growth prospects for localized chemical distribution and production partnerships.
- Localized Supply Chain Resilience: Opportunities to establish regional blending and distribution hubs to protect MRO facilities against global logistics bottlenecks and supply shocks.
- Military and Defense Readiness Hubs: Supplying specialized military-specification (mil-spec) maintenance chemicals, deicing fluids, and high-performance lubricants to allied defense networks.
- Private and Business Aviation Niche: Catering to the rapidly expanding fleet of private jets, regional turboprops, and business aircraft with specialized detailing and high-frequency servicing packs.
Digital Transformation and AI-Driven Inventory Optimization
- Smart Chemical Management Software: Integrating artificial intelligence into MRO inventory workflows to track chemical shelf-lives, prevent expiration waste, and automate reordering cycles.
- Automated Dispensing and Monitoring Systems: Partnering with maintenance facilities to install smart dispensing units that track precise chemical usage, reducing waste and hazardous exposure.
- Auditable Compliance Documentation: Software-enabled documentation tracing that ensures full regulatory traceability and transparent ESG reporting for airline operators.
Aerospace Maintenance Chemicals Industry Restraining Factors
High Costs and Strict Storage Requirements for Chemical Inventory
- Shorter Shelf Lives: Many specialized aerospace cleaners, adhesives, and sealants possess limited active lifespans, increasing the risk of product expiration and financial loss.
- Climate-Controlled Storage Demands: Preserving chemical stability requires specialized storage facilities with tightly regulated temperature and humidity controls, elevating overhead costs for MRO providers.
- Expensive Raw Materials: The high cost of specialized inputs and certified mil-spec formulations leads to significant procurement expenditures for operators.
- Inventory Holding Pressures: Maintaining adequate safety stock while managing the risk of degradation drives up working capital requirements for smaller maintenance facilities.
Stringent Regulatory Barriers and Compliance Mandates
- Rigid Mandates: Strict international regulatory frameworks continuously restrict or ban traditional, high-performance chemical ingredients like toxic solvents and harsh paint strippers.
- Costly Formulation Redesigns: Chemical manufacturers face immense financial and resource burdens to research, test, and market compliant eco-friendly alternatives.
- Complex Certification Barriers: Securing airworthiness approvals and OEM certifications for newly reformulated chemical products is a lengthy, capital-intensive process.
- Hazardous Waste Disposal Costs: Disposing of regulated chemical byproducts and wastewater involves substantial compliance fees and rigorous tracking frameworks.
Occupational Health Hazards and Strict Worker Safety Demands
- Toxic Exposure Risks: The hazardous nature of several traditional aviation chemicals poses severe health risks, such as respiratory issues and skin irritation, to maintenance technicians.
- Strict Safety Protocol Overhead: Mandated use of advanced personal protective equipment (PPE) and industrial ventilation systems increases operational complexity and labor friction.
- Liability and Insurance Pressures: Companies handling hazardous maintenance formulas face heightened legal liabilities, higher insurance premiums, and strict occupational safety audits.
Supply Chain Vulnerabilities and Geopolitical Trade Disruptions
- Raw Material Scarcity: Volatility in global chemical supply chains, periodic shortages of key petrochemicalderivatives, and trade tariffs disrupt production timelines.
- Cross-Border Logistics Friction: Official compliance checks and international trade friction between major trading partners delay the seamless distribution of specialized maintenance products.
- Single-Source Dependencies: Heavy reliance on limited specialized chemical refiners leaves MRO networks vulnerable to sudden factory shutdowns or regional trade disputes.
- Logistical Bottlenecks: Transporting hazardous or flammable maintenance chemicals involves complex regulatory hurdles, restricted freight routes, and elevated shipping expenses.
Aerospace Maintenance Chemicals Market Segmentation Analysis
By Product Type: Cleaners and Degreasers Lead Due to High-Frequency Application and Routine Maintenance Mandates
Cleaners and Degreasers: The cleaners and degreasers segment accounted for the largest revenue share in the market in 2025, and it is anticipated to register a significant CAGR during the forecast period.
Cleaners and degreasers hold a major share within the market for aerospace maintenance chemicals, driven by the constant need for routine exterior washing, interior cabin detailing, and heavy component degreasing. Since active aircraft accumulate aerodynamic drag-inducing grime, carbon deposits, grease, and hydraulic fluid residue during every flight cycle, operators rely heavily on specialized aqueous cleaners, solvent-based washes, and specialized spot removers. These chemicals ensure optimal aerodynamic efficiency, prevent long-term surface degradation, and satisfy strict regulatory requirements for passenger hygiene and structural visual inspections.
De-icing Fluids
De-icing fluids play a vital, mission-critical role in commercial and military aviation by ensuring safe operations during sub-freezing weather conditions and winter precipitation events. Type I, II, III, and IV glycol-based fluids are extensively utilized to rapidly clear frost, ice, and snow from critical flight control surfaces, wings, and fuselages prior to takeoff. The seasonal predictability of cold-weather operations, combined with zero-tolerance safety policies enforced by aviation authorities like the FAA and EASA, ensures sustained, high-volume demand for anti-icing and de-icing formulations across cold-climate regional hubs.
Paints, Coatings & Paint Strippers
Paints, coatings, and specialized paint strippers are essential for protecting aircraft metal and composite bodies against extreme environmental wear, UV radiation, and high-altitude corrosion. This segment includes durable exterior primers, functional mil-spec topcoats, and chemical paint removers necessary during scheduled heavy maintenance checks and full fleet rebranding. Although environmental mandates are accelerating the transition away from traditional hazardous chemical strippers toward eco-friendly, low-VOC, and media-blasting alternative methods, high-performance protective coatings remain essential for aerodynamic preservation and asset lifecycle extension.
Adhesives & Sealants
Adhesives and sealants are heavily utilized in both structural manufacturing and routine maintenance repair operations to bond advanced composite assemblies, seal fuel tanks, and weatherproof cabin windows. Formulated to withstand drastic fluctuations in pressure, temperature, and mechanical stress, aviation-grade sealants prevent fuel leaks, moisture ingress, and cabin depressurization. The growing integration of lightweight carbon-fiber composites across modern airframes continues to drive robust demand for specialized, chemically compatible aerospace maintenance chemicals.
Lubricants & Hydraulic Fluids
Lubricants and hydraulic fluids are important for maintaining the mechanical integrity, motion control, and friction reduction of highly stressed aircraft components, including landing gear systems, flight control actuators, and engine parts. Aviation lubricants, synthetic oils, and fire-resistant hydraulic fluids must operate under extreme thermal windows and heavy load conditions without breaking down. Regular fluid replenishment and comprehensive overhauls are mandatory compliance tasks, ensuring that high-performance lubricants remain a high-consumption category throughout an aircraft's operational lifespan.
Corrosion Inhibitors
Corrosion inhibitors are critical chemical formulations designed to protect vulnerable metallic structures, such as aluminum skin joints, interior frames, and hidden cavities, from moisture-induced oxidation and galvanic decay. Applied during routine maintenance checks and heavy structural inspections, contact and vapor corrosion inhibitors form resilient protective barriers that significantly extend the structural lifespan of aging fleets. With global commercial airlines keeping aircraft in service for longer periods, the demand for advanced, long-lasting corrosion prevention is expected to remain exceptionally strong.
By Formulation: Solvent-Based Leads Due to Superior Heavy-Duty Performance and Deep Penetration Capabilities
Solvent-Based: The solvent-based segment accounted for the largest revenue share in the market in 2025.
The solvent-based aerospace maintenance chemicals segment maintains the leading market share, primarily due to its superior performance in dissolving heavy grease, carbon deposits, hydraulic fluid residues, and specialized aerospace resins as compared to water-based alternatives. In critical MRO environments, solvent-based formulations are favored for their exceptionally fast evaporation rates, low surface tension, and deep penetration properties, which allow them to thoroughly clean intricate engine parts, landing gears, and mechanical assemblies without leaving moisture residues that could trigger flash rusting.
Furthermore, the segment growth is driven by several factors such as the expansion of commercial and military fleets along with rising R&D investments targeting advanced, lower-toxicity solvent variants and hybrid chemistries, among others.
Water-Based: The water-based segment is anticipated to register the fastest CAGR during the forecast period.
Water-based maintenance chemicals are experiencing rapid, high-growth adoption across the aerospace sector, primarily driven by stringent environmental regulations, airport wastewater controls, and occupational safety mandates. Modern water-based cleaners, eco-friendly surface washes, and aqueous degreasers are significantly utilized for routine interior cabin detailing and exterior fuselage cleaning. Moreover, factors including rising environmental compliance and corporate sustainability initiatives across global aviation MRO facilities and stricter limits on volatile organic compound (VOC) emissions enforced by regulatory bodies like the Federal Aviation Administration and the European Union Aviation Safety Agency are further driving the water-based aerospace maintenance chemicals segment growth.
By Application: Aircraft Exterior Maintenance Leads Due to Extreme Environmental Exposure and Strict Aerodynamic Standards
Aircraft Exterior Maintenance: The aircraft exterior maintenance segment accounted for the largest revenue share in the aerospace maintenance chemicals market share in 2025.
Aircraft exterior maintenance represents the largest application segment within the market, driven by the constant need to protect fuselages, wings, and control surfaces from harsh environmental exposure, UV radiation, and high-altitude icing. Regular exterior washing using specialized cleaners, paint strippers, and protective coatings is vital for eliminating aerodynamic drag-inducing residue, salt accumulation, and carbon build-up. Furthermore, strict regulatory standards requiring continuous visual inspections for micro-cracks and corrosion ensure that exterior cleaning and anti-icing formulations undergo high-frequency, routine application across all commercial and military fleets.
Aircraft Interior Maintenance
Aircraft interior maintenance focuses on preserving cabin hygiene, passenger safety, and aesthetic quality through the regular application of specialized upholstery cleaners, sanitizing agents, disinfectant wipes, and leather care chemicals. With rising global passenger volumes and heightened public health expectations, airlines prioritize deep-cleaning cycles for seating carpets, overhead bins, lavatories, and flight deck instruments. These aerospace maintenance chemicals must balance high germ-killing efficacy with non-corrosive properties to ensure they do not degrade sensitive cabin plastics, electronic panels, or composite materials.
Engine Maintenance: The engine maintenance segment is anticipated to register the fastest CAGR during the forecast period.
Engine maintenance is a critical segment that demands specialized compressor washes, heavy-duty degreasers, and carbon-removal solvents to ensure optimal thermal efficiency and prevent catastrophic mechanical failures. Turbine engines and internal components accumulate severe soot, oil varnishes, and atmospheric contaminants during flight, necessitating rigorous chemical cleaning during scheduled overhaul intervals. Since engine reliability is crucial for operational safety and fuel consumption, airlines and specialized MRO providers strictly utilize certified, high-performance aerospace maintenance chemicals that can withstand extreme operational tolerances.
By End User: Commercial Aviation Leads Due to Vast Fleet Sizes and Continuous Operational Flight Hours
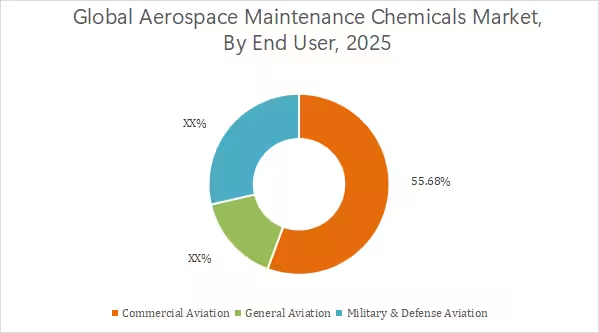
Commercial Aviation: The commercial aviation segment accounted for the largest revenue share of 55.68% in the market in 2025.
Commercial aviation holds the largest share of the aerospace maintenance chemicals market, driven by the rapid expansion of global passenger and cargo airline fleets, increasing flight frequencies, and strict regulatory mandates. Commercial airlines operate large-scale narrow-body and wide-body aircraft that undergo continuous, high-intensity flight cycles, accumulating heavy exterior grime, carbon, and fluid residues. To comply with rigorous airworthiness standards set by authorities like the FAA and EASA, and to fulfill consumer expectations for safety and cabin hygiene, commercial carriers routinely consume massive volumes of exterior washes, de-icing fluids, cabin cleaners, and specialized engine maintenance chemicals.
General Aviation
General aviation represents a stable consumer segment, including private business jets, regional turboprops, flight training schools, and charter aircraft. While individual aircraft usage volumes are lower than major commercial airlines, the aggregate number of private and regional planes requires a steady, localized demand for specialized detailing products, corrosion control compounds, and light surface aerospace maintenance chemicals. Owners and operators in this segment prioritize high-performance protective coatings, leather cleaners, and localized maintenance solutions to preserve asset value and ensure personal travel safety.
Military & Defense Aviation: The military & defense aviation segment is anticipated to register a substantial CAGR during the forecast period.
Military and defense aviation is a specialized, mission-critical end-user segment driven by uncompromising operational readiness standards, rigorous tactical deployments, and strict military specifications (mil-spec). Fighter jets, transport aircraft, military helicopters, and tactical support units operate in extreme, demanding environments that accelerate component wear and corrosion, requiring heavy-duty specialty lubricants, corrosion inhibitors, and high-performance chemical strippers. Since defense fleets must maintain peak combat readiness at all times, defense agencies enforce strict chemical maintenance protocols and secure long-term procurement frameworks with qualified maintenance chemical suppliers.
North America: Most Dominant Region
North America is estimated to reach over USD 4.94 Billion by 2034 from a value of USD 3.15 Billion in 2025 and it is projected to grow to USD 3.26 Billion in 2026.
North America holds the largest share in aerospace maintenance chemicals industry, supported by an expansive aerospace manufacturing base, massive commercial fleet, and presence of major airlines and maintenance, repair, and overhaul (MRO) companies. The region’s advanced aviation infrastructure, high volume of daily flight operations, and stringent regulatory oversight enforced by agencies like the Federal Aviation Administration (FAA) ensure consistent, high-value consumption of specialized cleaners, de-icing fluids, and corrosion control treatments.
United States
The United States is the primary country in the North American market, hosting major commercial airlines, global aerospace original equipment manufacturers (OEMs), and massive domestic cargo fleets. The country's strong emphasis on rigorous airworthiness standards, combined with heavy military and defense spending on tactical aircraft maintenance, drives continuous, high-volume procurement of specialized aviation chemicals, mil-spec coatings, and advanced hydraulic fluids.
Canada
Canada contributes significantly to the regional market, shaped by its vast geographic expanse, reliance on regional and bush aviation, and severe winter climates. The necessity for heavy cold-weather operations drives substantial, seasonal demand for high-performance glycol-based de-icing and anti-icing fluids. Additionally, Canada's robust aerospace manufacturing hubs in provinces like Quebec and Ontario maintain steady requirements for advanced structural adhesives, composite-compatible sealants, and precision maintenance solvents.
Europe:
Europe holds a major share of the global market, strongly propelled by rigorous environmental policies, aggressive sustainability targets, and the prominent presence of major industry players like Airbus. European MRO facilities operate under some of the world's strictest regulatory frameworks, such as the European Union's REACH mandates, which restrict hazardous chemical use. This regulatory environment accelerates regional investments into eco-friendly, low-VOC, bio-based cleaning formulations and advanced sustainable surface treatments across the region.
Germany
Germany holds a major share in the European aerospace maintenance chemical sector, driven by the presence of key MRO players like Lufthansa Technik and advanced engineering groups. The German market demands highly advanced, technically demanding chemical solutions, with a strong focus on high-temperature engine turbine washes, advanced structural adhesives, and multi-functional composite coatings. The country's strict focus on operational efficiency and aggressive carbon-reduction roadmaps drives rapid commercial implementation of eco-friendly maintenance chemicals.
United Kingdom
The United Kingdom aerospace maintenance chemicals market demand is mainly driven by its prominent civil aviation sector, robust defense industry, and global engine manufacturing leaders such as Rolls-Royce. This specialized industrial footprint generates considerable demand for high-value precision lubricants, hydraulic fluids, and aero-engine compressor washes designed to optimize fuel efficiency and prolong engine time-on-wing.
Asia Pacific: Fastest Growing Region
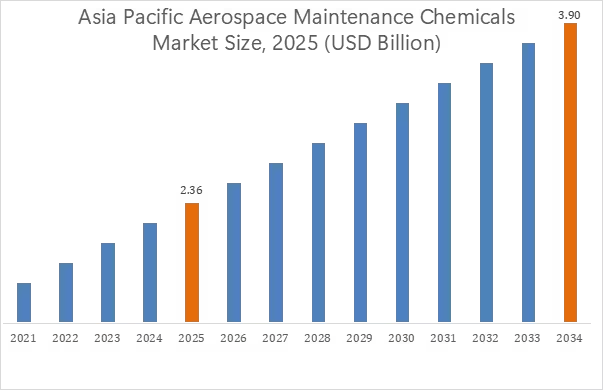
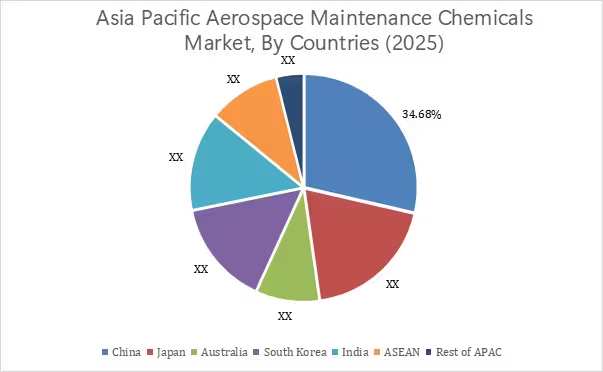
Asia Pacific region was valued at USD 2.36 Billion in 2025. Moreover, it is projected to grow to USD 2.46 Billion in 2026 and reach over USD 3.90 Billion by 2034. Out of this, China accounted for the maximum revenue share of 34.68%.
According to the aerospace maintenance chemicals market analysis, Asia Pacific is the fastest-growing regional market, propelled by surging air passenger traffic, low-cost carrier expansions, and heavy investments in airline fleet modernization. Moreover, the massive influx of new commercial aircraft deliveries into the region has accelerated the demand for local MRO infrastructure and maintenance supplies. Expanding tourism and commercial trade are driving significant investments into local aviation infrastructure, with international airlines shifting their heavy maintenance work to cost-effective MRO hubs across Southeast Asia.
China
China dominates the Asia Pacific aerospace maintenance chemicals market, driven by several factors including rapid urbanization, substantial state-backed investments in domestic aviation, rapidly growing domestic airlines, and the expanding rollout of its domestic commercial aircraft like the C919.
India
India represents one of the fastest-growing markets, driven by massive commercial aircraft orders by major domestic carriers, a rise in air travel demand, and government initiatives to position the country as a regional MRO hub. The rapid proliferation of domestic airlines necessitates constant line maintenance support, further increasing the local consumption of cabin cleaners, landing gear lubricants, exterior wash formulations, and other aerospace maintenance chemicals.
Japan
Japan aerospace maintenance chemicals industry is experiencing sustained growth, primarily focusing on rigorous fleet safety, defense aviation investments, and strict adherence to advanced maintenance schedules. Japanese airlines maintain extremely strict maintenance protocols, resulting in steady demand for premium-grade, low-toxicity surface treatments, advanced sealants, and composite-safe solvents, among others.
South Korea
South Korea maintains a robust position, driven by the presence of prominent commercial airlines, rising technological investments in aircraft maintenance efficiency, and an expanding domestic defense aviation sector, among others.
Latin America:
Latin America demonstrates steady aerospace maintenance chemicals market expansion, driven by growing civil aviation networks across countries like Brazil, and others. Moreover, the growing necessity to maintain aging commercial fleets and connect remote geographic regions through regional jets and turboprops sustains a regular demand for standard aircraft cleaning agents, deicing fluids, corrosion preventatives, and other maintenance chemicals.
Middle East and Africa:
The Middle East and Africa region is characterized by high-intensity hub operations and massive long-haul fleet concentrations, particularly across GCC countries. Extreme climatic conditions, such as high temperatures, desert dust, and coastal humidity, accelerate environmental wear and tear on aircraft surfaces. This requires frequent, rigorous washing, specialized exterior coatings, and advanced corrosion-control chemicals to maintain fleet integrity.
Leading Companies in the Aerospace Maintenance Chemicals Market
- Henkel AG & Co. KGaA (Germany)
- 3M (United States)
- PPG Industries Inc. (United States)
- BASF SE (Germany)
- Exxon Mobil Corporation (United States)
- Eastman Chemical Company (United States)
- Dow (United States)
- Socomore (France)
- Callington Haven Pty Ltd. (Australia)
- Arrow Solutions (United Kingdom)
Recent Developments Among Companies in the Aerospace Maintenance Chemicals Market
Acquisitions
- In April 2026,ConRoacquired Aerospace Chemical Supplies Ltd (ACS), aimed at expanding its distribution network for the aviation and defense sectors while enhancing supply chain resilience. The acquisition supports ConRo’s operational capabilities and logistics, while maintaining high-standard, compliant, and traceable material handling for customers
Aerospace Maintenance Chemicals Market Report Insights :
| Report Attributes | Report Details |
| Study Timeline | 2021-2034 |
| Market Size in 2034 | USD 14.62 Billion |
| CAGR (2026-2034) | 5.40% |
| Base Year | 2025 |
| By Product Type |
|
| By Nature |
|
| By Aircraft Type |
|
| By End-User |
|
| By Region |
|
| Key Players |
|
| North America | U.S. Canada Mexico |
| Europe | U.K. Germany France Spain Italy Russia Benelux Rest of Europe |
| APAC | China South Korea Japan India Australia ASEAN Rest of Asia-Pacific |
| Middle East and Africa | GCC Turkey South Africa Rest of MEA |
| LATAM | Brazil Argentina Chile Rest of LATAM |
| Report Coverage |
|
Key Questions Answered in the Report
How big is the aerospace maintenance chemicals market? −
The aerospace maintenance chemicals market was valued at USD 9.26 Billion in 2025 and is projected to grow to USD 14.62 Billion by 2034.
Which is the fastest-growing region in the market? +
Asia-Pacific is the region experiencing the most rapid growth in the market.
What specific segmentation details are covered in the aerospace maintenance chemicals report? +
The aerospace maintenance chemicals report includes specific segmentation details for product type, formulation, application, end user, and region.
Who are the major players in the market? +
The key participants in the market are Henkel AG & Co. KGaA (Germany), 3M (United States), PPG Industries Inc. (United States), BASF SE (Germany), Exxon Mobil Corporation (United States), Eastman Chemical Company (United States), Dow (United States), Socomore (France), Callington Haven Pty Ltd. (Australia), Arrow Solutions (United Kingdom), and others.
Overview
Reputation & Certifications

Our Services
- Market Intelligence & Forecasting
- Custom Research Solutions
- Market Entry Strategy
- Competitive Intelligence
- Customer Insights
- Industry Innovation Analysis
- Investment Advisory