Jump to Content
Target Drone Market - Size, Share, Industry Trends, and Forecasts (2026 - 2034)
Target Drone Market Size & Insights
The Target Drone Market size was valued at 5.50 (US$B) in 2025 and is projected to grow from 5.80 (US$B) in 2026 to 10.36 (US$B) by 2034, at a CAGR of 7.5% from 2026 to 2034, according to a recent report from Consegic Business Intelligence.
The target drone market growth is driven by several factors such as a rise in global defense spending and military modernization programs fueled by escalating geopolitical tensions, along with significant research and development investments in artificial intelligence (AI), autonomous navigation systems, electronic warfare simulation, and high-speed jet propulsion.
Target Drone Market Statistics:
- Current Market Size: USD 5.50 Billion
- Forecast Market Size: USD 10.36 Billion
- CAGR: 7.5%
- Largest Segment: Fixed-wing drones accounted for the largest revenue share in the market in 2025.
- Fastest-Growing Segment: The hybrid drones segment is anticipated to register the fastest CAGR during the forecast period.
- Largest Geographic Market: North America
- Fastest-Growing Geography: Asia Pacific
- Major Companies: QinetiQ Group Plc (UK), Airbus SE (Netherlands), Northrop Grumman Corporation (USA), Lockheed Martin Corporation (USA), Boeing (USA), Leonardo S.p.A. (Italy), BAE Systems plc (UK), Aerotargets International (Australia), Kratos Defense & Security Solutions Inc. (USA), Textron Inc. (USA), and others.
- Key Technological/Commercial Development: Integration of AI and Autonomous Swarm Simulation, Conversion Programs for Retired Fighter Jets, Advancements in Reusable and Modular Sub-Scaled Platforms, and Expansion of Electronic Warfare (EW) and Decoy Payloads.

Key Growth Drivers in the Target Drone Market
Escalating Geopolitical Tensions and Defense Budgets
- Rising Military Spending: Increased global defense allocations are prioritizing live-fire testing and tactical operational preparedness. Consequently, defense ministries are allocating substantial capital toward modern unmanned training infrastructure to maintain strategic combat readiness, further driving the target drone industry growth.
- Modernization Initiatives: Armed forces worldwide are actively upgrading their aging military inventories to counter advanced emerging threats. This modernization drive directly accelerates the acquisition of high-performance target systems capable of accurately validating next-generation defense assets.
- Border Security Focus: Heightened regional conflicts and border security concerns are driving demand for comprehensive surveillance and threat evaluation. Military forces rely heavily on aerial targets to test early-warning radar grids against potential cross-border intrusions.
- Strategic Defense Partnerships: Collaborative defense agreements and joint cross-border military exercises are accelerating technology transfers and procurement, thereby driving target drone market trends. These partnerships harmonize testing standards, ensuring allied nations uniformly adopt advanced target UAV technologies.
Advancements in Military Training and Realism Requirements
- Complex Threat Simulation: Military units require highly realistic aerial targets to accurately replicate modern cruise missiles, stealth aircraft, and high-speed fighter jets. Simulating these complex multi-vector flight profiles ensures that defense personnel are thoroughly prepared for contemporary combat realities.
- Advanced Air Defense Readiness: Greater emphasis on crew training and radar system validation necessitates repeatable, high-performance flight profiles, further driving the target drone market demand. Troops must repeatedly engage dynamic targets to minimize response times during actual combat engagements.
- Multi-Role Performance: Growing adoption of dual-purpose target UAVs capable of supporting electronic warfare(EW) and decoy exercises. These versatile platforms allow militaries to test radar jamming and communications disruption simultaneously during a single training sortie.
- Live-Fire Exercises: Increased frequency of live-fire missile drills drives constant replacement of target UAV inventories. Since live engagements routinely result in target destruction, defense forces require a steady supply stream of cost-effective replacement units.
Technological Innovations and Autonomous Integration
- AI and Swarm Capabilities: Integration of artificial intelligence allows target systems to autonomously compete with complex, multi-directional enemy swarm tactics. This capability considerably minimizes operator workloads while training air defense batteries to handle overwhelming, multi-point attacks.
- Supersonic and High-Speed Platforms: Technological breakthroughs in propulsion have led to the design of high-speed and supersonic target UAVs matching modern combat speeds. These platforms are vital for testing state-of-the-art interceptor missiles and supersonic defense shields.
- Autonomous Flight Control: Transition from purely remotely piloted setups to advanced semi-autonomous and fully autonomous operational modes is driving market growth. Autonomous pathfinding ensures that target UAVs execute intricate pre-programmed maneuvers without requiring continuous manual remote piloting.
- Payload Versatility: Modular architecture permits easy integration of threat-emulation payloads, scoring systems, and electronic countermeasures. This adaptability allows a single drone model to serve multiple training requirements by simply swapping out internal sensor packages.
Target Drone Market Opportunities
Development of Stealth and Hypersonic Targets
- Next-Generation Threat Replication: Creating low-observable targets that can accurately mimic modern 5th-generation stealth fighters and advanced radar-evading cruise missiles. These platforms use complex geometries to simulate the exact radar cross-sections of near-peer adversaries, giving air defense crews realistic combat practice.
- Hypersonic Speed Simulation: Engineering high-speed propulsion platforms capable of testing the interception capabilities of newly developed hypersonic air defense systems. Developing these high-velocity targets allows military forces to validate their reaction times against incoming threats that travel faster than traditional warning systems can track.
- Advanced Materials Integration: Using radar-absorbing composites and innovative geometries to cost-effectively replicate large-scale military aircraft structures. By applying these technologies to smaller airframes, manufacturers can significantly reduce production costs while maintaining the high-fidelity electronic profile needed for missile lock-on tests.
- High-Altitude Test Frameworks: Building target systems that operate efficiently in the upper atmosphere to evaluate space-edge and high-altitude interceptors. These specialized drones must survive thin atmospheric conditions and extreme thermal fluctuations to effectively test next-generation long-range surface-to-air missile systems.
Expansion in Emerging Economies and Defense Budgets
- Asia-Pacific Market Growth: Surging defense allocations and modernization initiatives across countries like India, China, and Japan create lucrative cross-border contracting channels.
- Middle Eastern Procurement Surge: Escalating investments in advanced air and missile defense infrastructure by Gulf nations drive consistent demand for state-of-the-art aerial targets.
- Strategic Defense Partnerships: Collaborative joint ventures between local defense contractors and established international aerospace firms foster technology transfer opportunities.
- Government Localization Policies: Domestic manufacturing mandates offer structural incentives for companies willing to establish local production hubs.
Diversification into Multi-Role and Commercial Applications
- Dual-Use Capabilities: Designing platforms that can effortlessly transition between target practice, electronic intelligence gathering (ELINT), and surveillance roles maximizes procurement appeal.
- Civil Security and Training Drills: Expanding market reach into law enforcement agencies, airport security training, and emergency response simulations offers lucrative opportunities from non-defense revenue streams.
- Aerospace Testing Services: Offering specialized contract-based target UAV flight services to private aerospace and defense developers who prefer outsourcing test infrastructure.
- Research and Academic Partnerships: Collaborating with universities and research institutions on aerodynamic testing provides early access to cutting-edge flight control patents.
Cost-Effective Conversions and Service-Based Models
- Retired Fighter Jet Refurbishment: Establishing specialized programs to convert decommissioned manned aircraft into automated aerial targets offers high-margin service contracts.
- Target-Drone-as-a-Service: Shifting from outright equipment sales to leasing or managed training service models allows smaller defense forces to adopt advanced systems.
- Reusable Sub-Scaled Platforms: Engineering highly durable, recoverable sub-scaled drones minimizes per-session training costs for budget-constrained military branches.
- Green Propulsion Integration: Developing eco-friendly or electric-powered propulsion systems helps defense clients meet internal sustainability mandates without sacrificing performance.
Target Drone Market Restraining Factors
High Procurement and Maintenance Expenditures
- Cost of Advanced Variants: While basic target UAVs are economical, highly sophisticated models, such as supersonic jets, stealth simulators, and heavy-payload platforms, incur steep procurement and manufacturing expenses.
- Budgetary Strain on Smaller Militaries: High upfront costs limit the adoption of advanced threat-simulation systems primarily to wealthy nations, restricting market expansion among defense forces with tighter budgets.
- Expensive Maintenance and Repairs: Maintaining delicate flight electronics, high-performance engines, and specialized tracking payloads demands constant funding for replacement components and technical servicing.
- Costly Large-Scale Exercises: Routine multi-drone deployment drills can become financially unsustainable over time when live-fire engagements result in the frequent total destruction of expensive units.
Technical and Operational Limitations
- Battery and Power Constraints: Electric or hybrid-powered target UAVs often face limitations in flight endurance and power distribution when attempting to simultaneously run heavy payloads like radar jammers or lasers.
- Navigation in Jammed Environments: Maintaining precise telemetry, control links, and autonomous pathfinding in heavily contested electromagnetic or GPS-denied training environments remains an engineering hurdle.
- Skilled Piloting Requirements: Operating high-speed or highly maneuverable target platforms safely requires rigorous specialized training to prevent accidental crashes and system failures during critical exercises.
- Payload Integration Complexities: Balancing aerodynamic stability while incorporating modular scoring systems, electronic warfare modules, and threat-emulation gear presents ongoing design challenges for developers.
Strict Regulatory Frameworks and Export Controls
- Rigid International Defense Controls: Stringent government policies and defense trade controls, such as U.S. ITAR or equivalent frameworks, tightly regulate cross-border sales, which may slow down global market distribution.
- Proliferation Restrictions: Governments place rigorous legal constraints on exporting advanced aerospace, guidance, and autonomous technologies to prevent sensitive military components from falling into adversarial hands.
- Lengthy Licensing Approvals: Obtaining compliance clearances and export licenses for international joint ventures or foreign military sales involves prolonged bureaucratic evaluation periods.
- Geopolitical Trade Barriers: Changing diplomatic alliances and bilateral sanctions can abruptly halt international supply chains or restrict market access to specific regions.
Target Drone Market Segmentation Analysis
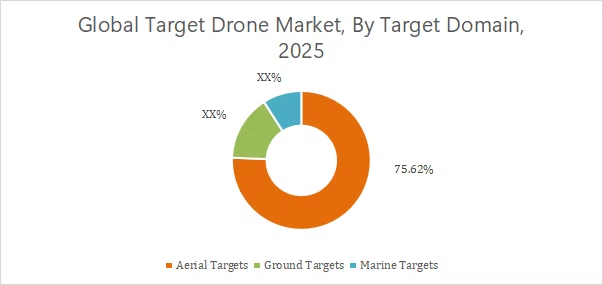
By Target Domain: Aerial Targets Lead Due to Their Unmatched Versatility, Rapid Deployment Capabilities, and Essential Role in Simulating Complex High-Speed Air-to-Air and Surface-to-Air Threat Scenarios
Aerial Targets: The aerial targets segment accounted for the largest revenue share of 75.62% in the market in 2025.
The aerial targets segment holds the dominant share of the global target drone industry. The segment growth is primarily driven by the increasing need for armed forces to replicate high-speed enemy aircraft, modern cruise missiles, and sophisticated stealth threats during live-fire weapon testing and combat readiness exercises. Aerial target UAVs provide unmatched operational flexibility, allowing military units to execute multi-vector flight maneuvers across extensive testing ranges with rapid launch and recovery turnarounds. Furthermore, ongoing technological integrations, such as advanced autopilot navigation, radar-cross-section modifiers, and AI-enabled swarm maneuvers, allow these systems to accurately test next-generation radar grids and air defense artillery.
Ground Targets
This segment is experiencing strong growth, due to rising training needs in anti-tank warfare and urban combat scenarios. Modern ground targets use advanced engineering to move autonomously, emit realistic heat signatures, and simulate enemy return fire. The steady expansion of this segment is driven by continuous modernization of ground forces, frequent tactical live-fire drills, and the rising integration of remote-controlled mobility platforms that simulate real-time enemy ground military exercises.
Marine Targets: The marine targets segment is anticipated to register the fastest CAGR during the forecast period.
This segment is expected to witness significant growth, due to expanding global naval forces and modern anti-ship missile defense needs. These maritime systems accurately simulate surface warships, hidden submarines, and fast-moving unmanned surface vessels. Navies use these targets to validate shipboard radar accuracy, calibrate automated deck guns, and test surface-to-air missile interceptors. Rising maritime border friction drives steady global investments in realistic sea-based threat replication.
By Drone Type: Fixed-Wing Drones Lead Due to Their Superior Speed, Extended Range, and Greater Payload Capacity
Fixed-Wing Drones: The fixed-wing drones segment accounted for the largest revenue share in the target drone market share in 2025.
Fixed-wing drones dominate the market, primarily driven by their aerodynamic capacity to achieve high speeds, cover extended operational ranges, and sustain long endurance flights. Military forces heavily rely on fixed-wing platforms as they can seamlessly mimic the dynamic flight profiles, radar cross-sections, and velocities of modern combat aircraft, supersonic jets, and incoming cruise missiles, making them crucial for rigorous weapon testing and advanced air defense training exercises.
Rotary-Wing Drones
Rotary-wing drones are mainly used for their vertical take-off and landing (VTOL) capabilities and agile maneuvering at low speeds and low altitudes. These platforms are primarily deployed to simulate hovering threats, such as military attack helicopters, low-flying unmanned aerial vehicles (UAVs), and localized surveillance choppers. Their ability to operate without traditional runway infrastructure allows defense forces to conduct realistic tactical drills in constrained or rugged environments where fixed-wing launches are impractical.
Hybrid Drones: The hybrid drones segment is anticipated to register the fastest CAGR during the forecast period.
The hybrid drone segment represents an expanding area of innovation, combining the vertical maneuverability of rotary-wing aircraft with the speed and cruising efficiency of fixed-wing systems. Modern defense procurement agencies increasingly favor hybrid solutions for target and decoy operations as they eliminate infrastructure dependencies while offering extended flight range. This versatility enables military operators to execute complex, multi-stage threat simulations using a single, adaptable platform across diverse geographic testing terrains.
By Operation Mode: Remotely Piloted Leads Due to Their High Reliability, Strict Human Oversight in Live-Fire Drills, and Established Military Certification Frameworks
Remotely Piloted: The remotely piloted segment accounted for the largest share of market revenue in 2025.
Remotely piloted drones are uncrewed aerial vehicles controlled by operators from a ground station or command center through secure communication links. They offer several benefits, such as minimizing human risk in hostile zones, delivering extended, persistent surveillance over vast territories, and executing highly precise targeting while maintaining lower operational costs than manned aircraft. Moreover, rapid technological advancements in artificial intelligence (AI), machine learning, and secure communication systems enable remotely piloted drones to operate deeper in contested environments while minimizing risks to human personnel.
Fully Autonomous: The fully autonomous segment is anticipated to register the fastest CAGR during the forecast period.
Fully autonomous drones are equipped with artificial intelligence (AI), which allows them to search, identify, and engage targets without human intervention. Unlike remotely piloted drones, which rely on a human operator to make the final strike decision, autonomous drones are capable of processing battlefield data onboard to execute missions independently. Moreover, key factors driving the segment include critical enhancements in AI and sensor integration, which enable real-time threat detection and autonomous target engagement with minimal human intervention. In addition, escalating global geopolitical tensions and the proven combat utility of unmanned systems in modern conflicts are also driving governments worldwide to significantly increase defense budgets and procure next-generation autonomous platforms.
By End Use: Combat Training Leads Due to the Critical Need for Realistic Air Defense Preparedness, Routine Live-Fire Exercises, and Dynamic Multi-Vector Threat Simulation
Combat Training: The combat training segment accounted for the largest share of market revenue in 2025.
The combat training segment holds the leading market share in the global target drone industry. This dominance is primarily driven by the continuous mandate for armed forces worldwide to maintain high operational readiness through regular, rigorous live-fire exercises. Military branches routinely deploy target UAVs to simulate complex, fast-moving hostile threats, such as incoming cruise missiles and advanced fighter jets, allowing ground and air defense crews to sharpen their tracking, reaction, and interception skills under authentic combat conditions.
Target and Decoy
The target and decoy segment utilizes specialized drones equipped with electronic warfare payloads, radar-cross-section enhancers, and thermal signatures to actively deceive enemy radar and missile tracking grids. Defense forces rely extensively on these platforms during tactical maneuvers to confuse hostile threat systems, protect high-value assets, and practice electronic countermeasures. The growing sophistication of modern electronic warfare has significantly accelerated the procurement of adaptable decoy drone variants.
Weapon Testing & Evaluation: The weapon testing & evaluation segment is anticipated to register the fastest CAGR during the forecast period.
The weapon testing & evaluation segment growth is mainly driven by the prevalence of defense contractors and military research agencies requiring precise, repeatable testing environments for newly developed missile systems and radar technologies. Target UAVs serve as crucial testing platforms that validate the accuracy, velocity handling, and destructive capability of next-generation interceptors. The constant evolution of defense tech pipelines ensures steady, long-term demand for high-performance target UAVs capable of withstanding stringent testing parameters.
Target Drone Market Regional Breakdown
North America: Most Dominant Region
North America is estimated to reach over USD 3.72 Billion by 2034 from a value of USD 1.99 Billion in 2025, and it is projected to grow to USD 2.10 Billion in 2026.
According to the target drone industry analysis, North America holds the leading share of the global target drone market, primarily driven by massive military spending and large-scale defense modernization initiatives. The region hosts a dense concentration of major aerospace manufacturers, fostering rapid technical innovation in stealth replication, autonomous flight software, and high-velocity systems. Ongoing joint-force live-fire exercises, massive research grants, and extensive testing infrastructures across vast training ranges ensure steady procurement pipelines.
United States
The United States is the primary country in the North American market, driven by the substantial budget allocations of the U.S. Department of Defense (DoD). High-value programs operated by the U.S. Army, Navy, and Air Force require highly sophisticated supersonic and hypersonic aerial targets to validate next-generation missile shields. Strategic policies enforcing strict domestic sourcing, along with significant multi-year contracts, provide long-term revenue stability for domestic target UAV manufacturers.
Canada
Canada contributes steadily to the North American market through active participation in joint continental defense exercises and strategic investments in modernized tactical training infrastructure. The Canadian Armed Forces prioritize adaptable, cold-weather-resilient unmanned systems to validate domestic and allied air defense readiness.
Europe:
Europe holds a significant share of the global market, propelled by collective security frameworks like NATO, joint military drills, and increased national defense budgets aimed at countering evolving regional threats. European defense agencies place strong emphasis on advanced electronic warfare (EW) payloads and modular, reusable target platforms.
Germany
Germany's target drone market growth is characterized by strict compliance standards, a strong focus on advanced automation, and ongoing modernization initiatives within the Bundeswehr. The country heavily invests in high-fidelity simulation technologies and joint European defense research programs to upgrade its air defense and radar evaluation capabilities.
United Kingdom
The United Kingdom target drone industry is driven by proactive defense modernization strategies and extensive test range facilities. The UK military frequently procures high-speed target UAVs to evaluate complex missile interceptors and train naval and air crews against high-velocity threats.
Asia Pacific: Fastest Growing Region
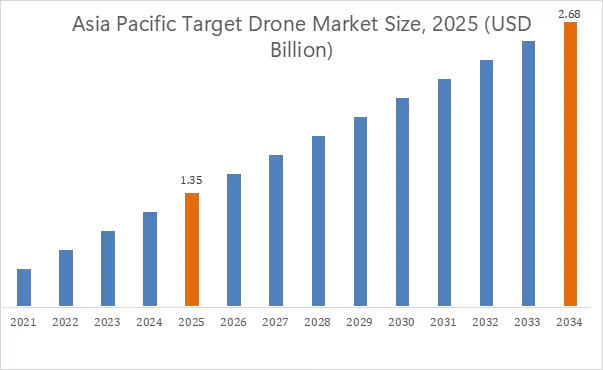
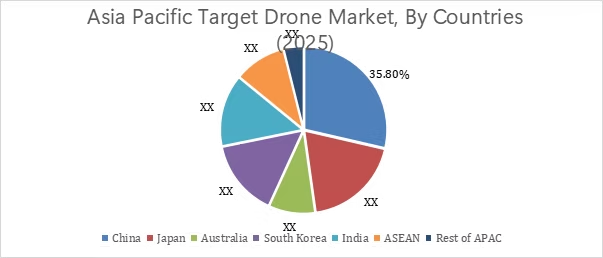
Asia Pacific region was valued at USD 1.35 billion in 2025. Moreover, it is projected to grow to USD 1.43 Billion in 2026 and reach over USD 2.68 Billion by 2034. Out of this, China accounted for the maximum revenue share of 35.80%.
The Asia-Pacific region is experiencing the fastest growth in the market for target drone, propelled by surging regional defense budgets, territorial tensions, and extensive military modernization drives. Countries across this region are rapidly expanding their live-fire testing ranges and procuring advanced autonomous target systems to sharpen their air defense preparedness.
China
China dominates a substantial share of the Asia-Pacific market, supported by massive domestic defense expenditures, a robust indigenous unmanned manufacturing ecosystem, and accelerated development of supersonic and swarm-capable target drones. Strategic emphasis on expanding naval and aerial combat readiness drives steady, large-scale local procurement.
India
India represents one of the fastest-growing markets, driven by rising defense allocations, indigenous defense manufacturing initiatives, such as Make in India, and the growing need to upgrade aging air defense grids along contested borders. The country actively invests in domestic target drone development programs to reduce import dependencies.
Japan
Japan's target drone market is expanding significantly, in response to shifting regional security dynamics and formal commitments to boost defense capabilities. The Japan Self-Defense Forces prioritize high-precision target systems to test advanced maritime and ballistic missile defense shields.
South Korea
South Korea exhibits robust demand for target drones, driven by continuous requirements to monitor and counter advanced asymmetric threats along the border. The country leverages domestic electronics and aerospace capabilities to field advanced aerial and ground target simulators.
Latin America:
The target drone market in Latin America is growing at a modest pace, primarily focused on tactical border surveillance training, anti-smuggling operational drills, and routine air force pilot qualifications. Brazil and Chile lead the regional demand, gradually moving toward acquiring multi-role, cost-effective target systems to maximize limited defense budgets. Growth in this market relies heavily on procurement partnerships with international aerospace vendors and integration of basic uncrewed target systems into naval exercises.
Middle East and Africa:
The Middle East and Africa region exhibits a highly diverse market landscape, with primary demand concentrated mainly in the Gulf Cooperation Council (GCC) nations. High defense spending in countries like Saudi Arabia and the UAE drives the procurement of premium, high-speed target platforms to validate newly acquired, complex western air defense missile shields. Conversely, other parts of the region focus mainly on cost-effective, basic target platforms for foundational training and localized counter-insurgency drill simulations.
Leading Companies in the Target Drone Market
- QinetiQ Group Plc
- Airbus SE
- Northrop Grumman Corporation
- Lockheed Martin Corporation
- Boeing
- Leonardo S.p.A.
- BAE Systems plc
- Aerotargets International
- Kratos Defense & Security Solutions Inc.
- Textron Inc.
Recent Developments Among Companies in the Target Drone Market
Partnership & Agreement
- In May 2025, Diehl Defence strengthened its partnership with RV Connex, a defence and security company based in Thailand. RV Connex and Diehl Defence signed a contract for delivering target drones and related services for conducting live firing tests with the IRIS-T air-to-air missile from Diehl Defence.
Target Drone Market Report Insights :
| Report Attributes | Report Details |
| Study Timeline | 2021-2034 |
| Market Size in 2034 | USD 10.36 Billion |
| CAGR (2025-2032) | 7.5% |
| By Target Domain |
|
| By Drone Type |
|
| By Operation Mode |
|
| By End Use |
|
| By Region |
|
| Key Players |
|
Key Questions Answered in the Report
How big is the target drone market? −
The target drone market was valued at USD 5.50 Billion in 2025 and is projected to grow to USD 10.36 Billion by 2034.
Which is the fastest-growing region in the market? +
Asia-Pacific is the region experiencing the most rapid growth in the market.
What specific segmentation details are covered in the target drone report? +
The report includes specific segmentation details for target domain, drone type, operation mode, end use, and region.
Who are the major players in the market? +
The key participants in the market are QinetiQ Group Plc (UK), Airbus SE (Netherlands), Northrop Grumman Corporation (USA), Lockheed Martin Corporation (USA), Boeing (USA), Leonardo S.p.A. (Italy), BAE Systems plc (UK), Aerotargets International (Australia), Kratos Defense & Security Solutions Inc. (USA), Textron Inc. (USA), and others.
Overview
Reputation & Certifications

Our Services
- Market Intelligence & Forecasting
- Custom Research Solutions
- Market Entry Strategy
- Competitive Intelligence
- Customer Insights
- Industry Innovation Analysis
- Investment Advisory